Korva is a scroll of the internet’s best ideas.
Zoom out from the bad moment

Tilt
Poker players trade chips every hand, so they see the risk in every single decision. The same setup lets them watch results like a stock ticker, feeling every downswing and upswing, and their emotions follow the path of the last few hands. Tilt is what happens when those emotions get lit up, shutting down the frontal cortex and producing really bad decisions.
The stock chart
A person's happiness over a lifetime ideally looks like Berkshire Hathaway stock: a general upward trend from its start that includes sharp downturns on given days. Look at only one day and it seems terrible.
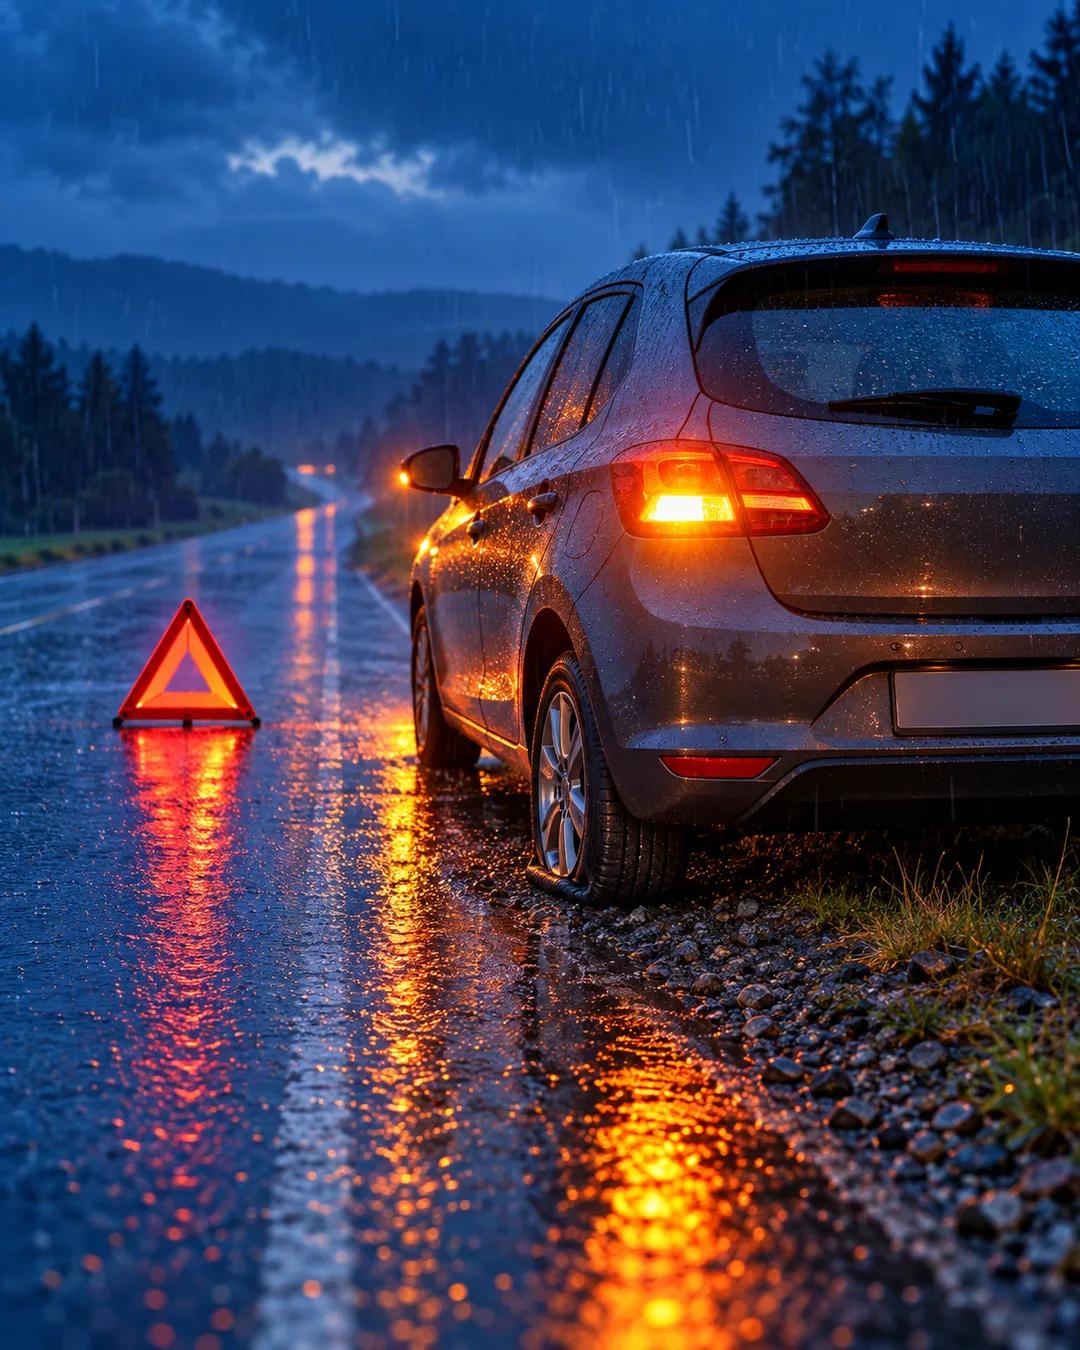
The flat tire
Picture a flat tire on the side of the road, in cold rain, with no jack and a roadside-assistance call that takes forever. The mind is deep inside that moment. Nobody stops to take the average of their happiness over the last three days, and a promotion three days earlier doesn't enter into it.
Look back on that same flat tire a year later and it more likely adds to happiness than subtracts from it, because it has become a really good cocktail party story.
What happens in the brain during tilt?
Neuroscientist Amy Arnsten reviewed the research on stress and the brain in a 2009 paper in Nature Reviews Neuroscience. She described how high levels of stress chemicals such as norepinephrine and dopamine weaken the prefrontal cortex, the region that supports planning and self-control. At the same time, the same chemicals strengthen the amygdala and other regions that drive fast, habitual reactions. The shift happens within moments of a strong stress response.
Why does a miserable moment become a good story?
Psychologist Richard Walker and colleagues studied what they called the fading affect bias. In their studies, the emotions tied to unpleasant events faded faster over time than the emotions tied to pleasant ones. Retelling an event also tends to shape it into a narrative with a beginning, a low point, and a resolution. This helps explain why stories about past mishaps are often the ones people enjoy telling.
Does watching results more often change risk-taking?
In 1995, economists Shlomo Benartzi and Richard Thaler proposed that investors who check their holdings frequently feel losses more often and take less risk. Uri Gneezy and Jan Potters tested the idea in a 1997 experiment. Participants who were shown their results after every round invested less in a risky gamble than those who saw results only every few rounds. The pattern is known as myopic loss aversion.
More from Talks at Google