Affirm Is American Express for the Internet
Visa and Mastercard provide the pipes, banks provide the loan, while Affirm and AmEx do both jobs and live with the credit risk.
 Business Breakdowns · Affirm: The Internet’s American Express - [Business Breakdowns, EP.249]
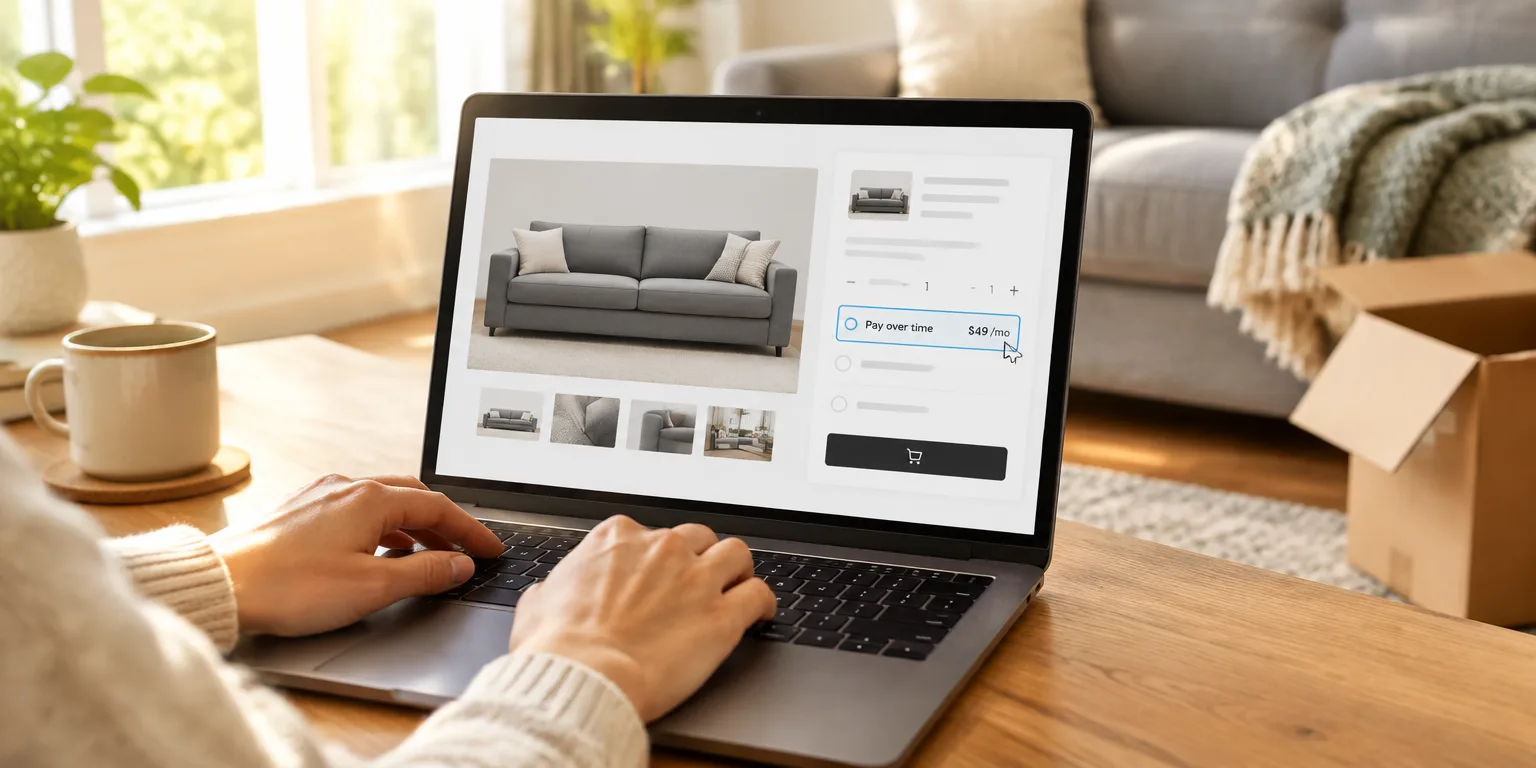
Picture a shopper buying a couch online. At checkout on a merchant site like Amazon or Target, she sees an offer for Affirm financing. These are typically reasonably material purchases. The average Affirm transaction is about $250.
That little button is why Fraser Christie, a growth investor who studies Affirm, calls the company the American Express built for the internet and online shopping. Affirm is built into merchant checkouts and makes the loan itself. When the shopper clicks, it handles the payment connection with the merchant and decides whether to lend her the money.
That combination separates American Express from Visa and Mastercard. Visa and Mastercard are, in Christie's phrase, purely the rails, meaning the pipes that move money from buyer to seller. They do not make the loan. A separate bank that issued the card extends the credit, collects interest, and absorbs the loss if the borrower does not pay.
American Express vertically integrates those two jobs, meaning it both runs the payment connection and lends the money itself. It maintains its own direct relationships with merchants around the world, and it also extends credit to its own cardholders. Affirm works the same way online, with direct integrations into merchant checkouts while the credit sits on top.
That is also what separates Affirm from many other lending apps, Christie argues. In those apps, a customer applies for money inside the app, the money is loaded onto an account or a virtual card, and the customer spends it anywhere. Christie would call those businesses lenders, not payment networks, because they lack the merchant link and the network effects. Affirm, by contrast, has vertically integrated the lending and the payments network.
The distinction has a cost. American Express has historically traded at a lower valuation multiple than Visa and Mastercard, reflecting the fact that it also carries loans on its own books. Affirm, which is built into merchant checkouts and makes the loan itself, lives with that same tradeoff.
Questions people ask
If I buy something with a Visa card, who is actually lending me the money?
The bank that issued your Visa credit card lends you the money. That bank sets your credit limit, charges interest, and takes the loss if you default. Visa runs the payment network and earns fees for doing so.
How does Affirm make money if it sits at checkout?
Merchants pay Affirm a fee for each transaction, and borrowers often pay interest on longer term loans. Affirm says it charges no late fees, no compounding balances, and no deferred interest. Its profit measure subtracts funding costs, processing costs, and credit losses from that merchant and interest income.
Why does making the loan change how investors value the company?
For investors, combining payments and lending means also owning the losses. A pure network like Visa grows mainly on payment volume, while a vertically integrated lender like Affirm or AmEx also rises and falls with defaults and interest rates. That credit component is why the market has valued the integrated model at a discount.