Most Checking Accounts Lose Money for Your Bank
The typical account brings in about $107 in fees but costs up to $400 to maintain, and banks treat the difference as marketing.
 PolyMatter · How America’s 4,488 Banks Work
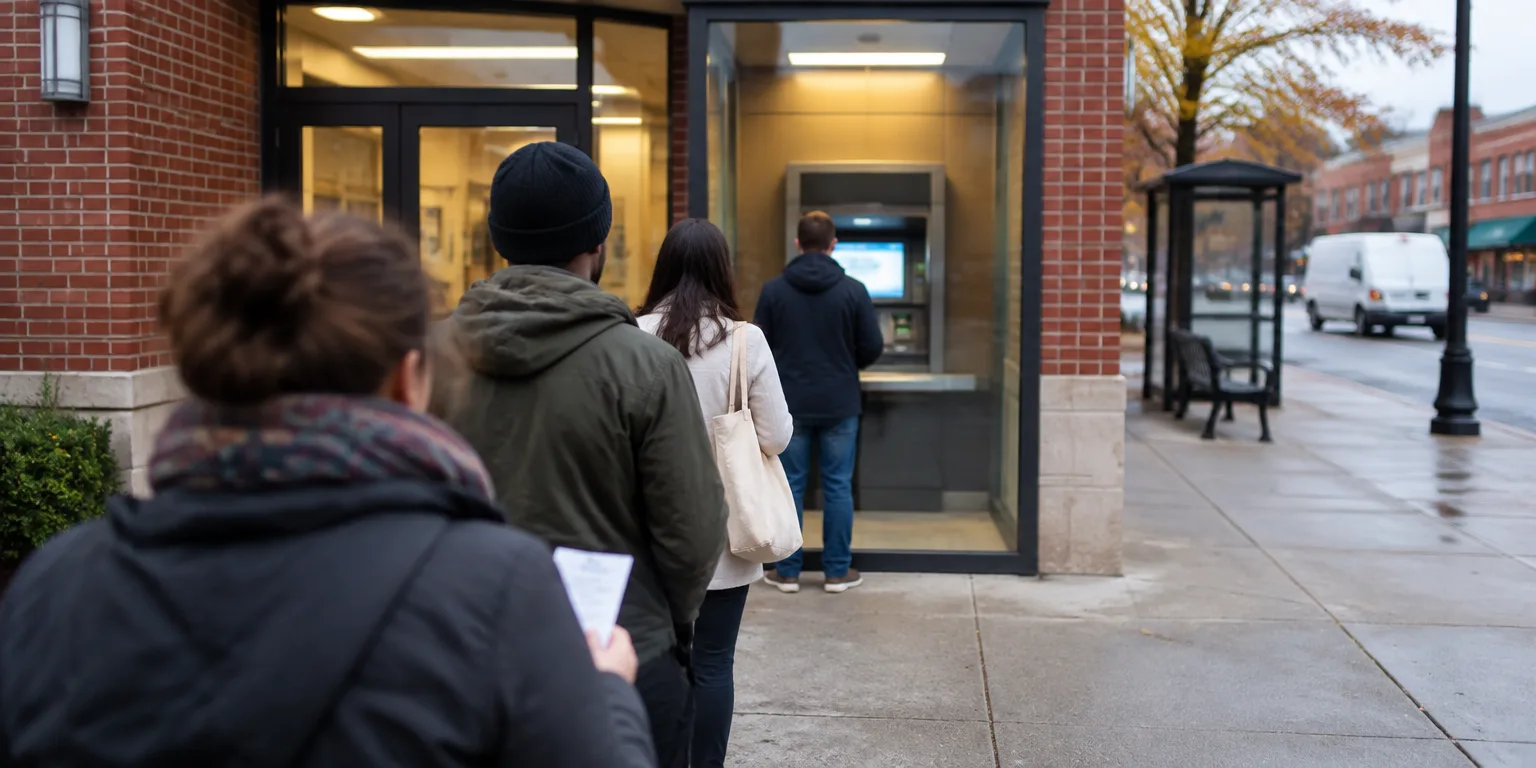
Picture the line at the cash machine on payday. The typical checking customer keeps about $1,300 in the account, stops by the ATM twice a month, with no home loan on the horizon.
That customer is not a moneymaker. A typical account produces roughly $107 a year in service and overdraft fees, according to one analysis of bank fees. It costs $250 to $400 a year to service that same customer, by some estimates. For the customer in the middle, the bank earns zero, or less than zero.
So why keep the account open? Start with the building itself. Paying for the building and its workers changes little whether a branch serves 3,100 accounts or 3,200. One more unprofitable account does not add much cost, and one fewer does not save much.
Banking rests on lasting ties with customers. Most people dislike thinking about banks, so they dislike switching banks. There is a decent chance your first bank will be the last one you use.
The average branch collects half the deposits it will ever hold in its first three years. After that, success is mostly about keeping the customers it already has.
That is why a bank can afford to wait. An account could cost the bank more to maintain than it earns for 23 years. If in year 24 that customer comes back for a mortgage, the wait may have been worth it. Viewed that way, those early losses are marketing, as affordable as backing the neighborhood youth baseball squad and as useful for earning a town's trust.
Questions people ask
What actually costs $250 to $400 a year to service me?
Mainly real estate and staffing. A branch needs a building and people whether it serves many accounts or few, so those fixed costs accrue even when your balance is low and you visit only now and then.
Why don't banks just raise fees to cover the cost?
Some try, but competition limits how far they can go. If monthly fees or overdraft charges get too high, customers leave for a rival bank or a credit union, and regulators and lawmakers also watch fee practices closely.
When does a customer finally become profitable?
When you borrow or keep larger balances. A mortgage, auto loan, or business loan produces years of interest income, and larger deposits give the bank more money to lend. That is why a customer who looks unprofitable early on can become very profitable later.