Your credit card judges you once, Affirm judges every purchase
Each loan has a fixed rate and end date, so higher rates mean fewer new loans, not more expensive old ones.
 Business Breakdowns · Affirm: The Internet’s American Express - [Business Breakdowns, EP.249]
A credit card sets a spending limit one time, and that limit can then cover many purchases without a fresh review.
Affirm reviews each purchase as it happens. Fraser Christie of Sandstone Global Investment says that purchase by purchase check is meant to give better outcomes for borrowers, because every loan has a set rate and a set end date.
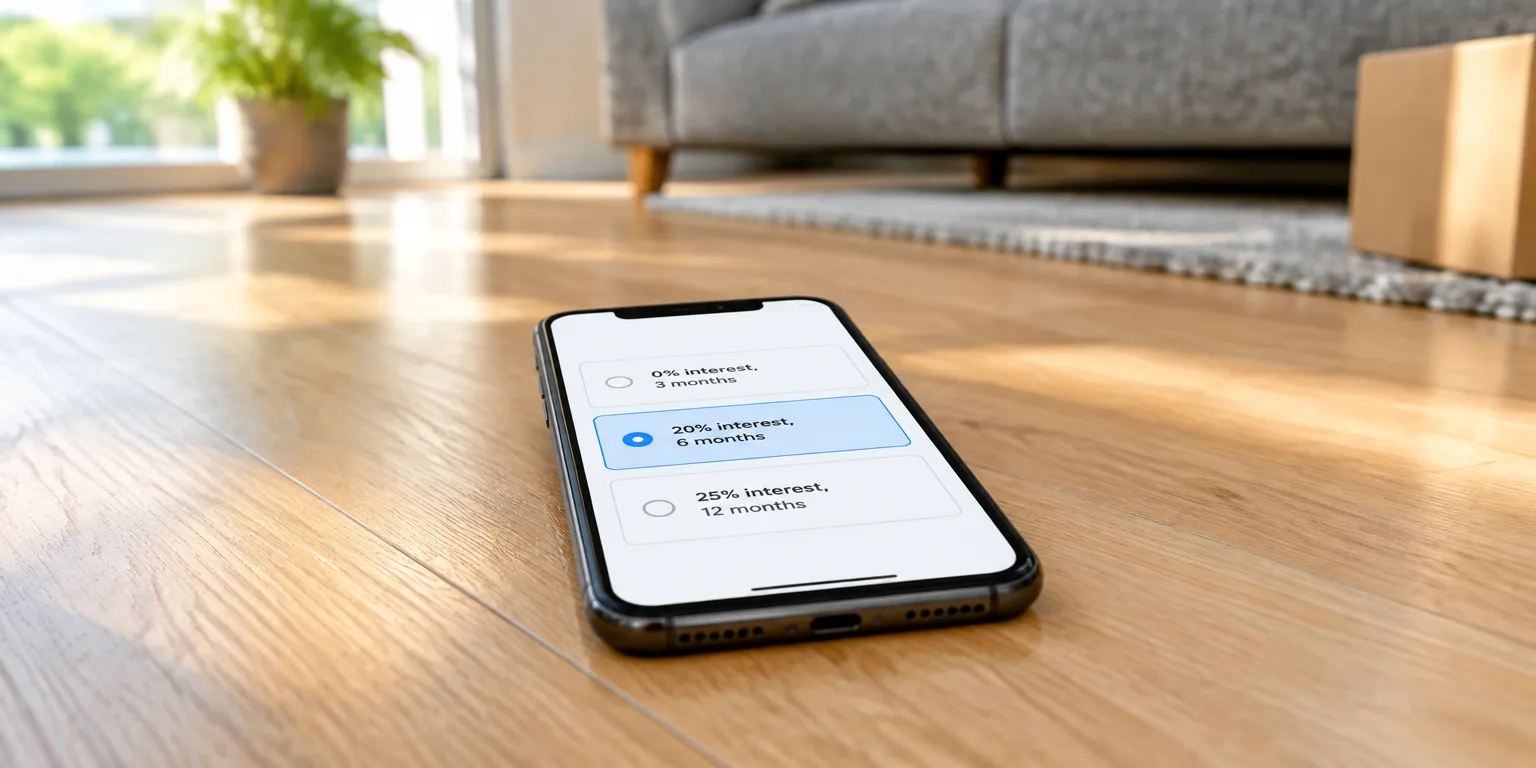
Here is how Christie describes it working at an online checkout. A shopper sees possible plans for that item, such as 0% interest over three months, 20% over six months, or 25% over 12 months. To apply, the shopper provides a name, birth date, and just the final four numbers from the Social Security number.
Affirm then combines details about that basket, the store, the size, and the items, with credit history to finalize the offer. The rate never moves, payments follow a set calendar, and the debt clears to zero on a set date.
That structure looks different from cards, where half of American holders carry a balance from month to month and the average balance is about $7,000. Christie points to variable rates, compounding, and late fees that can leave people paying down debt for years.
The difference shows when borrowing costs rise. Christie uses a 12-month, $500 couch loan as an example. At 15% interest, the loan can make sense. If funding costs push the required rate to 25%, Affirm stops offering loans to borrowers like that one, so growth slows for a quarter or two while existing loans stay at their original terms.
By contrast, he says cards hold large balances on variable rates that compound, so a rate rise can produce a broad wave of credit losses. Affirm does not reprice old loans. It writes fewer new ones, which Christie argues is healthier and lower risk.
Questions people ask
Does using Affirm affect my credit score?
Yes, in most cases. Affirm usually runs a soft credit check, which does not affect your score, to decide on that purchase. It may report the loan and your payment history to credit bureaus, so paying on time can help build credit and missing payments can hurt it.
If the loan ends at zero, how does Affirm make money?
Affirm makes money in two main ways. Stores pay it a fee for handling the checkout and bringing a sale they might otherwise lose. On longer loans that charge interest, it also collects that interest from the borrower.
What happens to my Affirm loan if interest rates go up?
You keep the terms you agreed to at checkout. Your monthly amount and interest rate do not change, even if market rates rise. The adjustment happens on future purchases, which may be offered at higher rates or declined.