Korva is a scroll of the internet’s best ideas.
Pay in multiples, not IRR

Why IRR wears down
Years of experience with IRR targets pointed to the same problem: at some point they create misalignment between management teams and investors, even with the best management teams. It is mathematical. A 35 percent IRR, or whatever the threshold is, gets harder to maintain as a business grows.
A self-regulating schedule
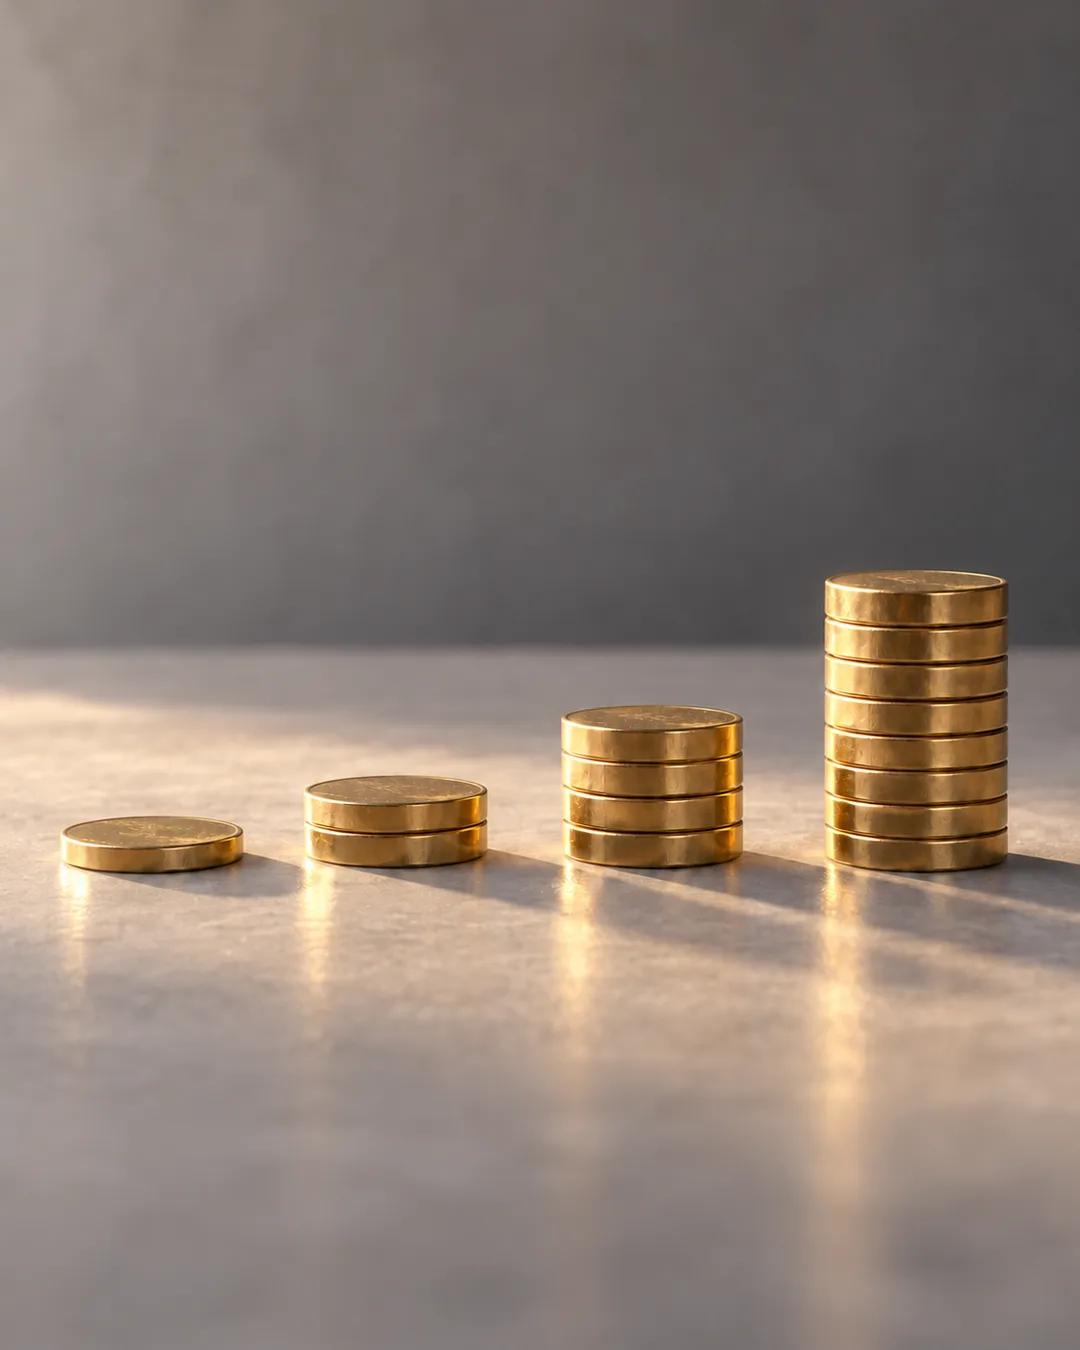
A pay schedule based on net multiples of invested capital regulates itself. If returns drift down to something less exciting, the investors still control the board and the final call on whether to exit. The CEOs are also likely to be the ones who lead the decision to sell if they aren't convinced the business can keep growing. The schedule is tied to doubles: 2X, 4X, and so on.
Ownership that rises
It also reverses the usual dilution in venture, where a founder starts with as much ownership as they will ever have, the pie grows, and their share shrinks, which creates poor incentives. Here a CEO's ownership percentage rises with each doubling of the multiple on capital, so the team running things gets more skin in the game as the outcomes grow.
Why does IRR reward quick exits?
Internal rate of return is an annual percentage, so the same profit looks better the sooner it arrives. Money that doubles in two years works out to roughly 41 percent a year. Money that takes ten years to double works out to roughly 7 percent a year. Both outcomes are the same 2X multiple on the money invested.
Why does venture dilute founders over time?
Each time a startup raises money, it issues new shares to the incoming investors, so every existing owner's percentage shrinks. Venture investors commonly buy a sizable slice of the company in each funding round, often a tenth to a quarter. Stock option pools for employees are carved out of the founders' ownership as well. By the time a venture-backed company goes public, its founders often hold a minority stake.
More from Joys of Compounding