Korva is a scroll of the internet’s best ideas.
Unlimited loans make fraud repeatable
How the fraud works
In this kind of fraud, two people work together against a lender. One buys a house for pretty cheap and sells it to a close friend, who agrees to pay a price far above what the house is worth. Maybe an appraiser even signs off on the inflated value. Using that fake price, the friend applies for a very large mortgage.
With DSCR loans there is no limit on how many loans a borrower can get, so the same trick could run over and over. Repeated hundreds of times, with the pocketed money hidden, it could leave the pair millions of dollars richer. One person ends up loaded with debt and eventually stops paying, and the homes go into foreclosure, after tens of millions of dollars, perhaps as much as $100 million, in additional loans has already been taken out.
Why Baltimore
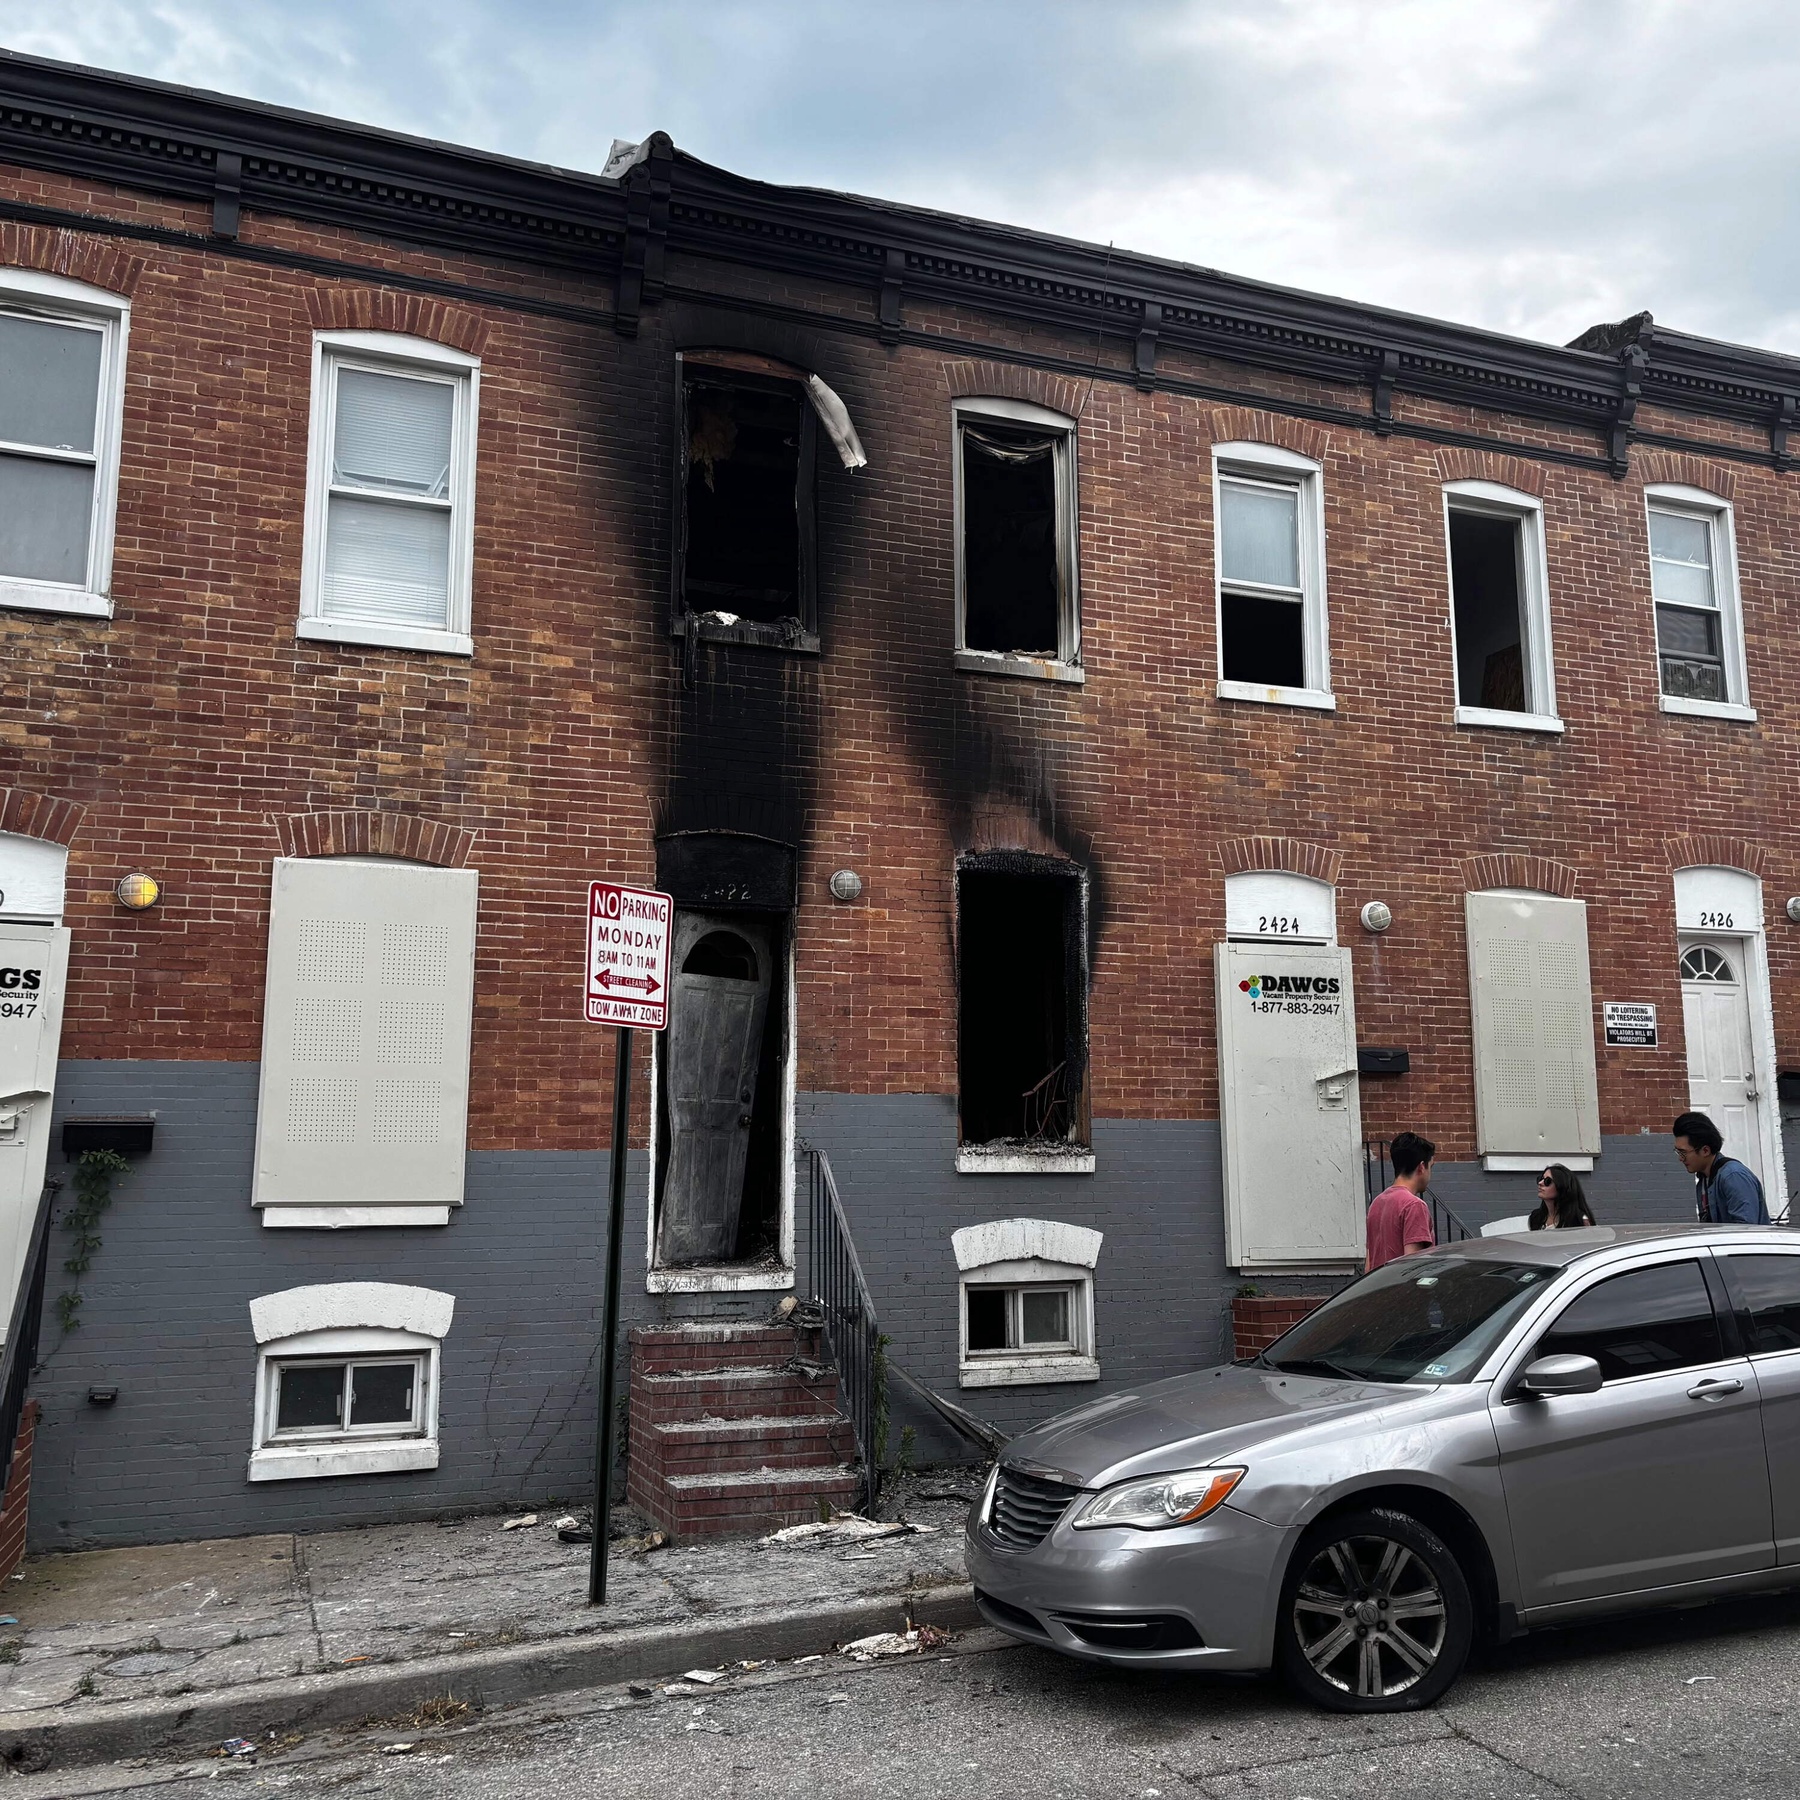
Baltimore is an easy place to try it. Some blocks are in good shape and others are filled with abandoned, vacant homes, and out-of-town private lenders trying to close loans quickly may see them all as looking the same.
What is known
This is the theory two Baltimore Banner reporters formed about the 700-home portfolio, and it remains only a theory. The FBI has since opened an investigation into Eliezer Gold, Benjamin Idles, and others, and private lenders have put those names on a blacklist. Neither man would comment.
How does an inflated appraisal produce a bigger loan?
Lenders usually lend a percentage of a home's appraised value, called the loan-to-value ratio. A higher appraisal raises the amount the lender will fund against the same house. If the loan defaults, the lender can recover only what the house actually sells for, and the gap between the loan and that sale price is its loss. The FBI describes property flipping with inflated appraisals as a mortgage fraud scheme.
Why are home values hard to pin down in Baltimore?
Appraisers value a house by comparing it with recent sales of similar nearby homes, called comparables. Where blocks mix well-kept and vacant houses, the sale prices of nearby homes can differ widely. Foreclosure and distressed sales, which often close well below market value, also feed into the comparables. That spread makes two reasonable appraisals of the same house differ by a wide margin.
More from Planet Money