A 2.6 Times Return Can Still Fail to Raise the Next Fund
For mid-2010s funds, that strong result ranked only in the second quartile, and some backers now favor fewer managers.
 Dry Powder: The Private Equity Podcast · When Fund Selection Is No Longer Enough w/ HarbourVest’s John Toomey
A friend's fund that turned every dollar into $2.60 at a 24% IRR sounds like a triumph, but in private equity it can still leave the manager unable to raise its next fund.
John Toomey, the chief executive of investment firm HarbourVest, says he has business school friends who have spent 15 or 20 years in the industry and cannot understand why a record like that fails to attract new money.
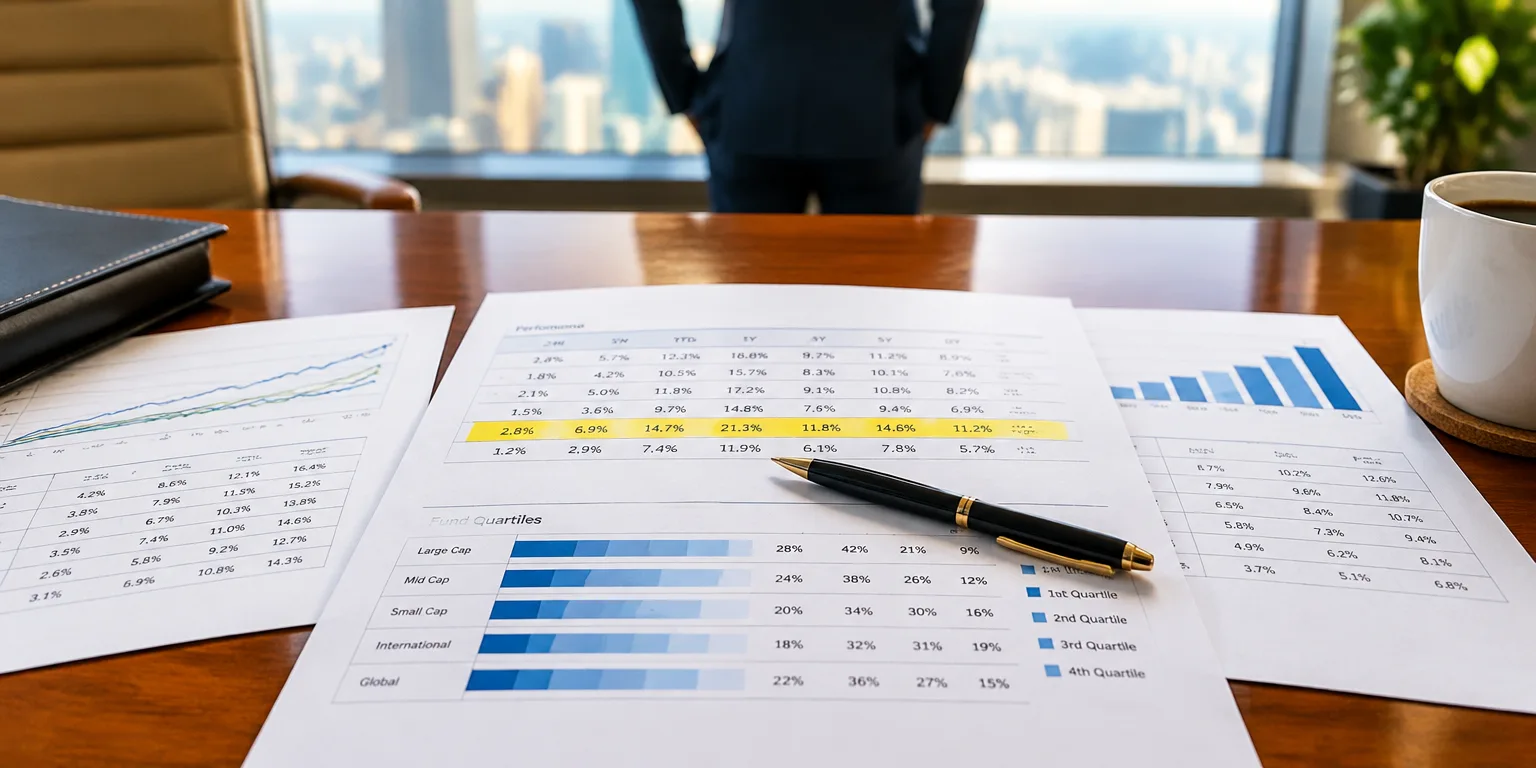
The answer, he says, is ranking. For funds that started investing around 2015 to 2017, a 2.6 times return with a 24% IRR was only a solid second quartile result, meaning rivals in the same vintage year did better.
That grading curve matters because limited partner capital, from pensions and endowments that back private funds, is scarce and fiercely competitive. Toomey says some investors are trying to reduce complexity by handing investment work to outside specialists or by backing fewer managers, making fundraising even harder.
Questions people ask
What does second quartile mean?
Private funds are usually ranked against others that started in the same year and split into four equal groups. First quartile is the top 25%, second quartile is the next 25%, and so on, so a second quartile fund beat half the field but still lagged the top performers.
What is a vintage year?
It is the year a fund started investing. Toomey points to funds from around 2015, 2016 and 2017 as his example.
Why would an investor walk away from a good return just to have fewer managers?
General context: working with fewer managers can reduce complexity and workload. Toomey says some investors are looking everywhere they can to reduce the complexity of managing their programs.